
Blog
Empowering Startup Success through Data Aggregation
Understanding the Role of Data Aggregation in Startups
At its core, data aggregation serves a dual purpose. First, it enables startups to gain a comprehensive view of market trends, customer behaviors, and competitive landscapes. Second, it facilitates informed decision-making, a crucial element for any business but especially for startups where resources are often limited and every decision counts.
In the context of fintech, data aggregation takes on additional layers of importance. This sector thrives on data: financial transactions, customer financial histories, market trends, regulatory changes, and so forth. By effectively aggregating this data, fintech startups can unlock insights that are not just valuable, but often pivotal for their success.
The Strategic Advantages of Data Aggregation
The benefits of data aggregation for startups and new entrants in the fintech space are manifold. Here are some key advantages:
- Enhanced Customer Insights: By aggregating data from various sources, startups can develop a deeper understanding of their customers. This includes spending habits, financial needs, and preferences. Such insights are invaluable for tailoring products and services, improving customer experience, and ultimately driving customer loyalty.
- Risk Management and Compliance: Fintech startups operate in a heavily regulated environment. Data aggregation helps in monitoring and complying with various regulatory requirements. By having a consolidated view of financial transactions and customer activities, startups can more effectively identify and mitigate risks.
- Market Trend Analysis: The ability to aggregate and analyze data from multiple sources enables startups to identify and capitalize on emerging market trends. This can be crucial for staying ahead of the competition and for making strategic decisions about product development and market positioning.
- Personalization and Product Development: In today's market, personalization is key. Data aggregation allows startups to tailor their offerings to meet the specific needs and preferences of their target audience, leading to more effective and competitive products.
- Operational Efficiency: By aggregating operational and financial data, startups can identify areas of inefficiency and opportunity within their own processes, leading to cost savings and improved operational performance.
Implementing Data Aggregation: Best Practices
For startups keen on harnessing the power of data aggregation, here are some best practices to consider:
Choose the Right Tools and Technologies: Selecting the appropriate data aggregation tools is critical. This includes software that can handle large volumes of data from diverse sources and can provide real-time insights.
Ensure Data Quality and Integrity: The value of aggregated data heavily depends on its quality. Startups must establish processes to ensure the accuracy, completeness, and consistency of the data they collect.
Prioritize Data Security and Privacy: With great data comes great responsibility. Startups must ensure compliance with data protection regulations and implement robust security measures to safeguard customer data.
Cultivate a Data-driven Culture: Encouraging a culture that values data-driven decision-making across the organization is essential. This involves training staff, establishing clear data governance policies, and fostering an environment where data is seen as a key strategic asset.
Leverage Advanced Analytics and AI: To fully capitalize on data aggregation, startups should consider employing advanced analytics and artificial intelligence. These technologies can provide deeper insights and predictive capabilities that can significantly enhance decision-making and innovation.
Real-world Applications and Success Stories
The application of data aggregation in fintech startups is not just theoretical. Numerous success stories illustrate its potential. For instance, consider a fintech startup that leveraged data aggregation to develop a personal finance management tool. By aggregating data from users’ bank accounts, credit cards, and investment portfolios, the tool provides personalized financial advice, helping users to make better financial decisions.
Another example is a startup that used aggregated data to develop a risk assessment model for lending. By pulling in data from various sources, including credit scores, transaction histories, and even social media activity, the startup was able to assess the creditworthiness of individuals who might be overlooked by traditional banks.
Navigating Challenges and Ethical Considerations
While the benefits of data aggregation are clear, it’s not without its challenges. Startups must navigate issues related to data privacy, security, and ethical use of data. This includes ensuring compliance with regulations such as the General Data Protection Regulation (GDPR) in Europe and similar laws elsewhere. Additionally, there is the challenge of avoiding bias in data collection and analysis, ensuring that the insights derived are fair and representative.
Conclusion
For startups in the fintech sector, data aggregation is not just a tool; it’s a strategic asset that can propel them to new heights. By effectively gathering and synthesizing data from various sources, startups can gain invaluable insights into customer behavior, market trends, and operational efficiencies. This enables them to tailor their products and services more effectively, make informed strategic decisions, and stay ahead in a highly competitive market.
However, leveraging data aggregation is not a set-and-forget strategy. It requires ongoing attention to the quality and integrity of data, adherence to evolving regulatory standards, and a commitment to ethical data practices. Startups must invest in the right tools and technologies, foster a data-driven culture within their organization, and continuously adapt to changing market dynamics.
In essence, the successful implementation of data aggregation strategies can transform a startup from a new market entrant into a formidable player in the fintech ecosystem. It allows them to compete not just on the strength of their products or services, but on their ability to deeply understand and rapidly respond to the needs of the market and their customers.
As the fintech landscape continues to evolve, data aggregation will undoubtedly play an increasingly crucial role. Startups that master this domain will not only survive but thrive, carving out their niche in a future where data-driven insights are the currency of success. Thus, for emerging fintech players looking to make their mark, embracing and excelling in data aggregation is not just an option, but a necessity.
Frequently Asked Questions
What questions should I ask a bank data aggregator before signing?
The questions worth asking before you sign fall into three areas. On redundancy: what happens to your users if the aggregator goes down, and does the provider handle failover routing or does that become your problem? On pricing: what does the cost model look like at 1,000, 10,000, and 100,000 users, and are there volume tiers or commitments that change the math at scale? On portability: who owns the connection data, what does a migration look like if you need to switch providers, and how long does that typically take? If your product touches business or commercial accounts, ask specifically which institutions are covered and whether those connections are API-based or screen scraping. And keep in mind: just because a bank is covered on a provider's platform doesn't mean every type of account or data is covered. If you want to dive deeper, check out our blog on questions we typically hear from new fintech builders.
Why wouldn't I just build direct integrations with each financial institution?
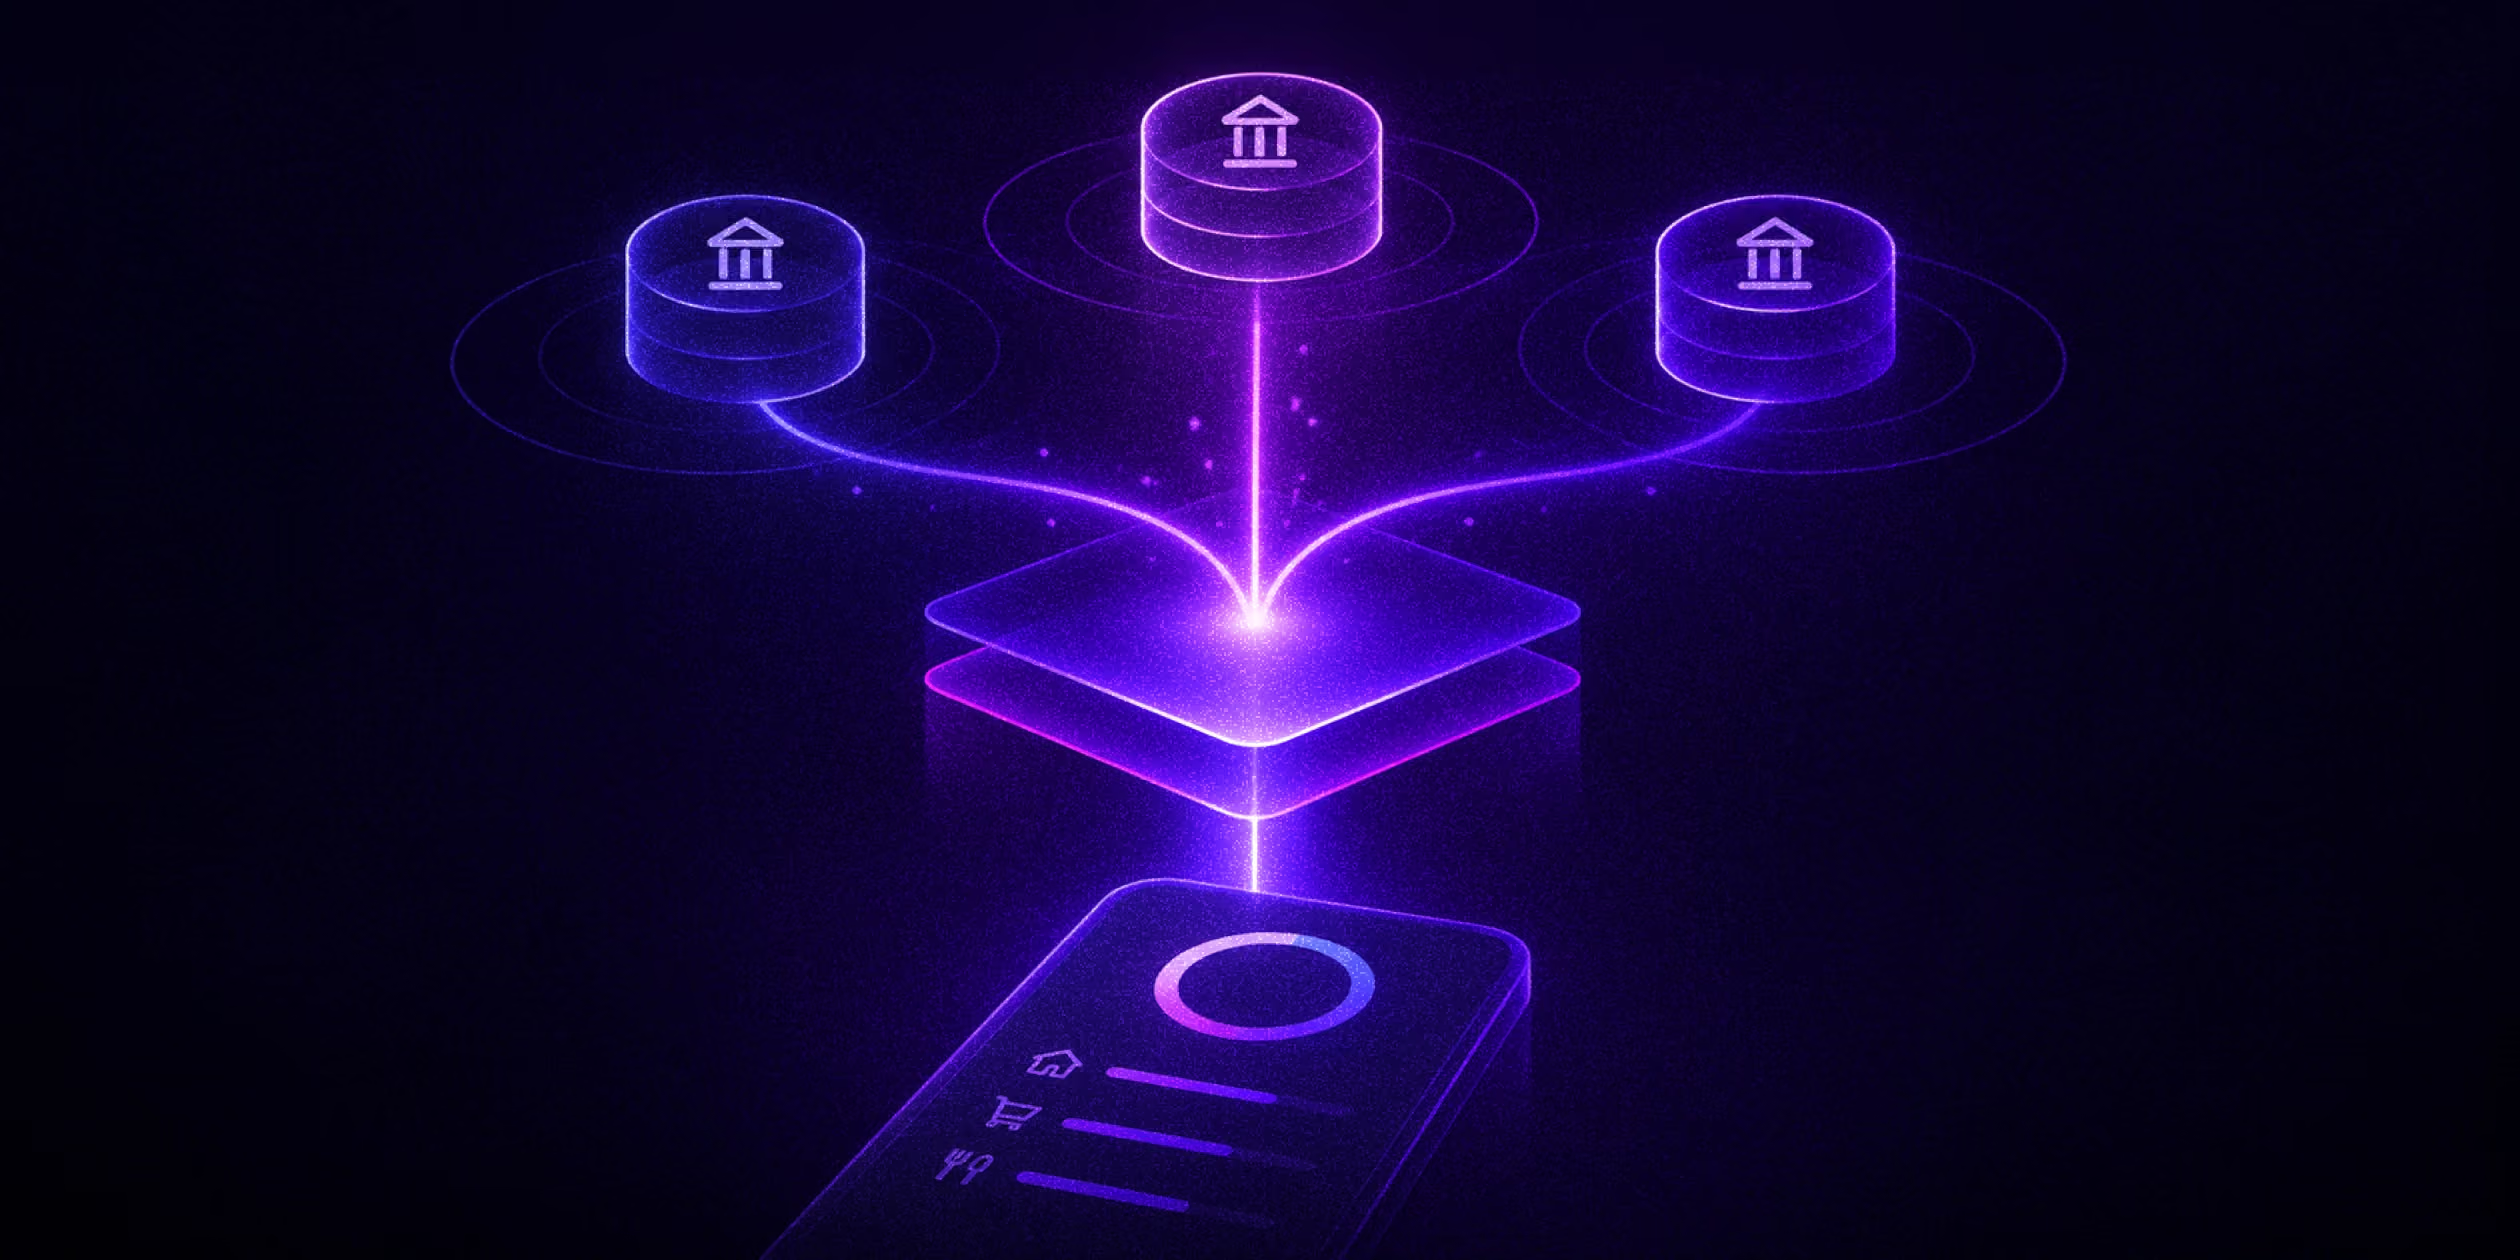
Building one-off integrations with banks or financial institutions is technically complex and resource-intensive. APIs vary significantly in terms of reliability, formatting, and security standards. Aggregators help solve that by offering normalized, consistent data through a single API.
If you want access to multiple providers for broader coverage or redundancy, you'll typically need to negotiate individual contracts with each one. That adds legal, procurement, and compliance complexity to your development process.
Quiltt solves both layers of friction. You get a single integration and a single contract that unlocks access to multiple financial aggregators, so your team can move faster without getting buried in technical or legal hurdles.
What are common use cases for aggregation in FinTech products?
Aggregation powers features like personal finance dashboards, income verification, credit modeling, cash flow analysis, and lending decisions. It also enables smoother onboarding and faster user activation by reducing manual data entry.